
For insurance carriers in the peak months of hurricane season, one of the quieter cost drivers in a CAT deployment isn’t the volume of files. It’s the small number of large loss files that get worked as though they were daily files.
Every hurricane deployment produces a mix of file types. Residential single-family losses carry the volume. But every event also produces a smaller category that behaves differently: commercial property, multi-family and mixed-use structures, residential total losses where the path to reconstruction is substantially more complex than a routine claim, and the business interruption component a commercial loss can carry. These are large loss insurance claims, and they need a different operational discipline than daily property files.
In our experience, the deployments that generate avoidable returns, supplements, and desk rework hours in the months afterward are very often the ones where large loss files ran through the same structure as everything else. The damage in the field is real. The documentation depth the file needs is different, and the difference doesn’t announce itself during the inspection.
For claims leadership managing CAT capacity through the rest of the season, this is worth thinking about now, while the vendor conversations are still open.
Why Large Loss Files Behave Differently
The distinction isn’t the dollar value of the loss. It’s the operational complexity of what the file has to contain.
A daily property file usually involves one primary cause of loss, a defined set of damaged components, and a relatively contained investigation. The adjuster can work the file end to end in a straightforward sequence: inspection, scope, narrative, estimate, submission.
A large loss file operates in a wider frame. Commercial roofs may involve multiple slopes and materials across far more square footage than any residential structure. Multi-family properties involve multiple units, shared systems, and coordination with property managers and tenants. Residential total losses involve full contents inventory and additional living expense considerations that a routine file never touches. Commercial losses can also carry business interruption, which is handled to the degree the file requires; where the accounting runs complex, a forensic accountant is typically brought in.
The documentation the file needs is proportionally deeper. The scope is more complex. The narrative has more variables to work through. The photo record has to cover more territory with the same consistency. And the carrier’s determination downstream rests on all of it holding up under closer scrutiny than a routine file receives.
The damage in the field is real. The documentation depth the file needs is different, and the difference doesn’t announce itself during the inspection.
Where the Large Loss File Outgrows the Daily Structure
The failure mode here isn’t a lack of skill. The daily adjuster is typically competent, disciplined, and capable of good work at the file complexity they’re calibrated to. The failure mode is structural: a deployment organised around inspection count, with no separate track for the files that need more, will route a commercial roof to whoever is next on the board.
That is how many CAT deployments are organised, and it produces a consistent set of gaps.
Scope discipline thins out. A large loss property adjuster who has spent years on commercial and complex residential files knows what to look for in ways that don’t transfer from daily experience: which building components tend to hide damage, which materials call for closer inspection, which code implications affect reconstruction, which contents categories need itemisation a routine file never requires. When the structure hasn’t matched the file to that experience, those things get learned in the field, and the file carries the gaps.
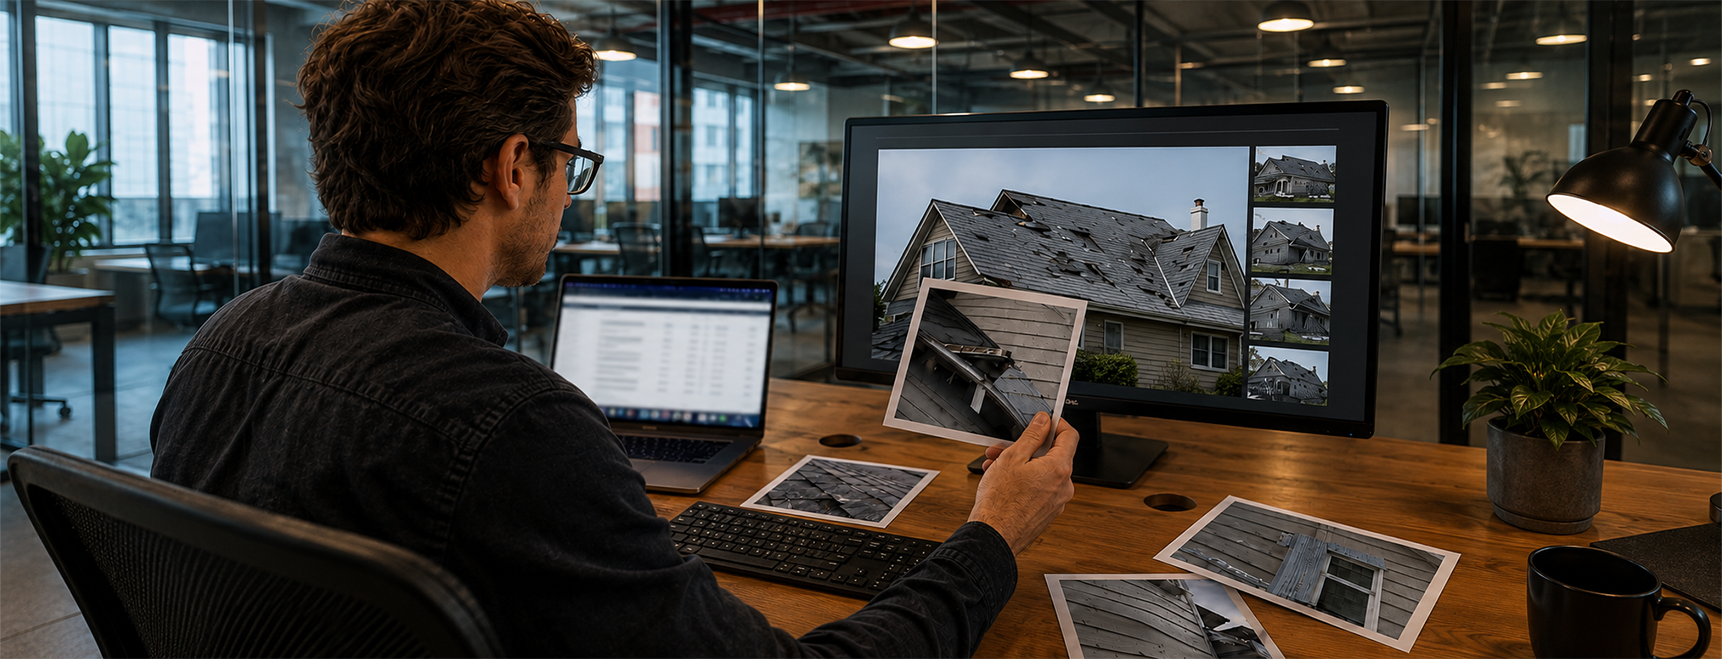
Documentation depth stays calibrated to the wrong file. A photo report built for a routine residential inspection covers what that inspection requires. The same approach on a commercial roof or a multi-family property produces a record that would have been complete for a house, and is materially incomplete for the structure actually inspected. The gap surfaces weeks later, when the file is reviewed.
Integration stops at the property line. A large loss file typically carries more contributors than a daily file: engineers, contractors, contents specialists, sometimes public adjusters and attorneys, each producing their own account of the loss. A structure built for daily work is set up to inspect and document. A large loss file needs someone set up to integrate everything the file contains into one coherent record, and to hold it together across the weeks or months of continuing adjustment.
Timing pressures compound. Large loss files carry different clocks than daily files. Additional living expense runs on residential total losses. Proof of loss deadlines matter differently. A large loss file worked at a daily pace misses timing considerations the file’s own structure requires.
Each of these gaps is manageable when the file is matched to the right structure. Each of them compounds when it isn’t.
A deployment can look productive on the activity dashboard and tell a different story on the large loss files.
Where Weak Large Loss Handling Costs the Carrier
The operational cost of a mismatched large loss file shows up in specific places, and they tend to appear well after the deployment closes.
Supplements at higher volumes. A large loss file with thin original documentation produces supplements that compound against a larger original scope. A commercial roof file that missed adjacent damage, code implications, or matching considerations at first inspection produces a supplement that can rival the original scope.
Avoidable returns that consume desk hours and stretch cycle time. Complex files with incomplete documentation come back for correction, and the correction cycle on a large loss file involves more people, more coordination, and more desk hours than a routine return. A large loss file rebuilt through returns and supplements closes weeks or months later, not days, and that shows in the carrier’s operational metrics well into the following quarter.
Relationship cost with the insured. The policyholder on a large loss is dealing with a more disruptive event than a routine claim. A file that is handled well earns the carrier real loyalty. A file that is handled poorly produces a reputational cost that outlasts the individual claim.
What a Complete Large Loss File Documents
- A full property inspection scaled to the structure’s actual size and complexity, with the exposures the carrier’s guidelines call for covered in the photo record
- A scope that reflects everything the file contains, integrated into a single record rather than fragmented across reports
- A contemporaneous narrative capturing what the adjuster observed, including code considerations, matching considerations, and reconstruction implications
- Timing considerations documented: additional living expense, proof of loss deadlines, and continuing-adjustment requirements
- Photo record depth matched to the file’s complexity, with baseline and context photos of non-damaged areas throughout
- → Photo report, narrative, and estimate reviewed against each other before submission
What Carriers Should Be Asking Vendors Now
If your book has meaningful commercial, multi-family, or complex residential exposure while the season is still running, the vendor conversation worth having is about how large loss files get handled, separately from how daily files get handled.
Ask your vendor which adjusters on their roster are qualified for large loss work, and what that qualification rests on. Ask them to walk you through their documentation standard on a large loss file specifically: what the pre-delivery review covers, and how it handles the additional ground a complex file carries.
The vendors who handle this well can describe their large loss operation in operational specifics. The vendors who treat large loss as an extension of daily work usually describe their daily operation instead.
How Aspen Approaches Large Loss Hurricane Claims
Since 2008, our experience handling hurricane claims has reinforced one consistent observation: large loss files hold up under review when the structure around them was built for the file, not borrowed from the daily workflow.
At Aspen, large loss files go to specifically qualified adjusters within our desk-led Full Claim Handling model: adjusters whose experience is in commercial, multi-family, and complex residential work. The field adjuster conducts the inspection and develops the estimate. The desk adjuster owns carrier communication, file development, quality review, and submission. On a large loss file, that means integrating whatever the file contains into a single coherent record before it is submitted.
Every large loss file passes through the three-document review before it reaches the carrier desk: the photo report, the narrative, and the estimate read against each other for consistency. On a complex file, that review covers whatever the file requires. One story, told three ways, at the depth the structure demands.
The field does the work on the ground. The desk owns the outcome. One dedicated liaison per carrier: no account layers, no ticket queues.
If your post-event reconciliation shows supplement volume or avoidable returns concentrated on your commercial, multi-family, or complex residential files, the place to look first is how those files were assigned. A large loss file handled inside a structure built for it produces a different outcome than one that ran through the daily workflow.
Planning for hurricane surge capacity?
Learn how Aspen matches large loss files to the qualified adjusters and the file review discipline the work requires.
Discuss CAT Capacity with Aspen → aspenclaims.com
FAQ
What makes a claim a large loss claim?
Large loss insurance claims are defined less by the dollar figure than by operational complexity: commercial property, multi-family and mixed-use structures, residential total losses where reconstruction involves multiple parties and timing requirements a routine daily claim doesn’t carry, and the business interruption component a commercial loss can bring with it.
What is the difference between a daily adjuster and a large loss adjuster?
The daily adjuster vs large loss adjuster distinction is one of experience calibration. A large loss property adjuster has worked commercial and complex residential files and knows which components hide damage, which materials need closer inspection, and which code implications affect reconstruction. The skill set is the same; the frame it’s applied in is wider.
Why do large loss hurricane claims produce more supplements?
Because the original scope is larger and the documentation has to cover more ground. When a large loss hurricane claims adjuster assignment is worked at daily depth, adjacent damage, code implications, and matching considerations get missed at first inspection and surface later as supplements against a larger base.
What should a carrier ask a large loss independent adjuster partner?
Candidates who clear the ADAPT typically progress to a Group Discussion and Personal Interview (GD/PI), followed by a medical assessment and a simulator test. Each stage builds a fuller picture of the candidate’s suitability for the iCPP training pathway.
How does a property damage insurance claim adjuster document a large loss file?
The same three documents as any file: photo report, narrative, and estimate, with depth scaled to the structure, everything the file contains integrated into a single record, timing considerations recorded, and all three reviewed against each other before submission.